Let recurring payments flow effortlessly into your business
Your best customers are the ones who come back without being asked twice. But relying on them to remember to reorder, renew, or return means leaving revenue on the table unnecessarily.
Share this article


Recurring payments automate the billing process, keeping customers engaged, and creating a predictable revenue stream that compounds over time without requiring action from either side.
But setting up recurring payments is one thing. Making them work consistently, reducing failed transactions, and building a model that actually retains customers is another.
In this article, we cover what recurring payments are, how they work, and the strategies that help you get more out of them.
What is a recurring payment?
A one-time payment lets customers pay for an order immediately. A recurring payment establishes a repeated charge on a fixed or flexible schedule, in exchange for ongoing access to a product or service.
The most common form is a subscription, but recurring payments also cover installment plans, automatic top-ups, and any model where the customer gives upfront authorization for future charges.
Recurring payments can be processed through any payment method your business already supports: credit or debit cards, direct debit, or digital wallets. And depending on your product, service, and customer profile, you can collect payments daily, weekly, monthly, quarterly, or on entirely custom terms.
Types of recurring payments
Not all recurring payments work the same way. There are two main categories, and understanding the difference matters for how you set them up.
Merchant-initiated transactions (MIT)
The customer provides their payment details and gives authorization upfront. From that point, you initiate the charge on a regular basis and the customer doesn't need to take any action.
One important note: the first payment in any MIT setup must be fully authenticated — either via a standard authorization or a Zero Authorization. This initial authentication serves as the cardholder's explicit consent to store their credentials and authorize future charges, which is essential for dispute resolution down the line.
This is the model behind most subscriptions: streaming services, SaaS platforms, supplement deliveries, and meal kits. It also covers delayed charges such as hotel billing for minibar use after checkout and automatic installment payments through Buy Now, Pay Later.
Customer-initiated transactions (CIT)
Here, the merchant stores the customer's payment details securely after the first transaction. When the customer decides to make a follow-up purchase, they can select their saved payment method and confirm — no need to re-enter card details.
This is the model behind one-click purchases on Amazon. The customer is in control of when the charge happens, and stored payment details make the process significantly faster. Note that by default, 3D Secure authentication is still required for customer-initiated payments — though exemptions may apply for tokenized transactions depending on the risk assessment.
Supported recurring models
The distinction between MIT and CIT isn't just theoretical. It directly shapes how each payment is processed, authenticated, and classified. At MultiSafepay, this translates into three supported recurring models:
- One-click payments (CIT): The customer selects stored payment details for a faster checkout experience.
- Subscriptions (CIT → MIT): The first payment is customer-initiated and requires full 3D Secure authentication. Subsequent charges are merchant-initiated and do not require re-authentication — the token handles everything.
- Unscheduled payments (CIT → MIT): The first payment is customer-initiated and requires full 3D Secure authentication. Subsequent event-triggered payments — for example, a mobile top-up when the customer runs out of credit — are merchant-initiated and processed automatically without re-authentication.
How do recurring payments work?
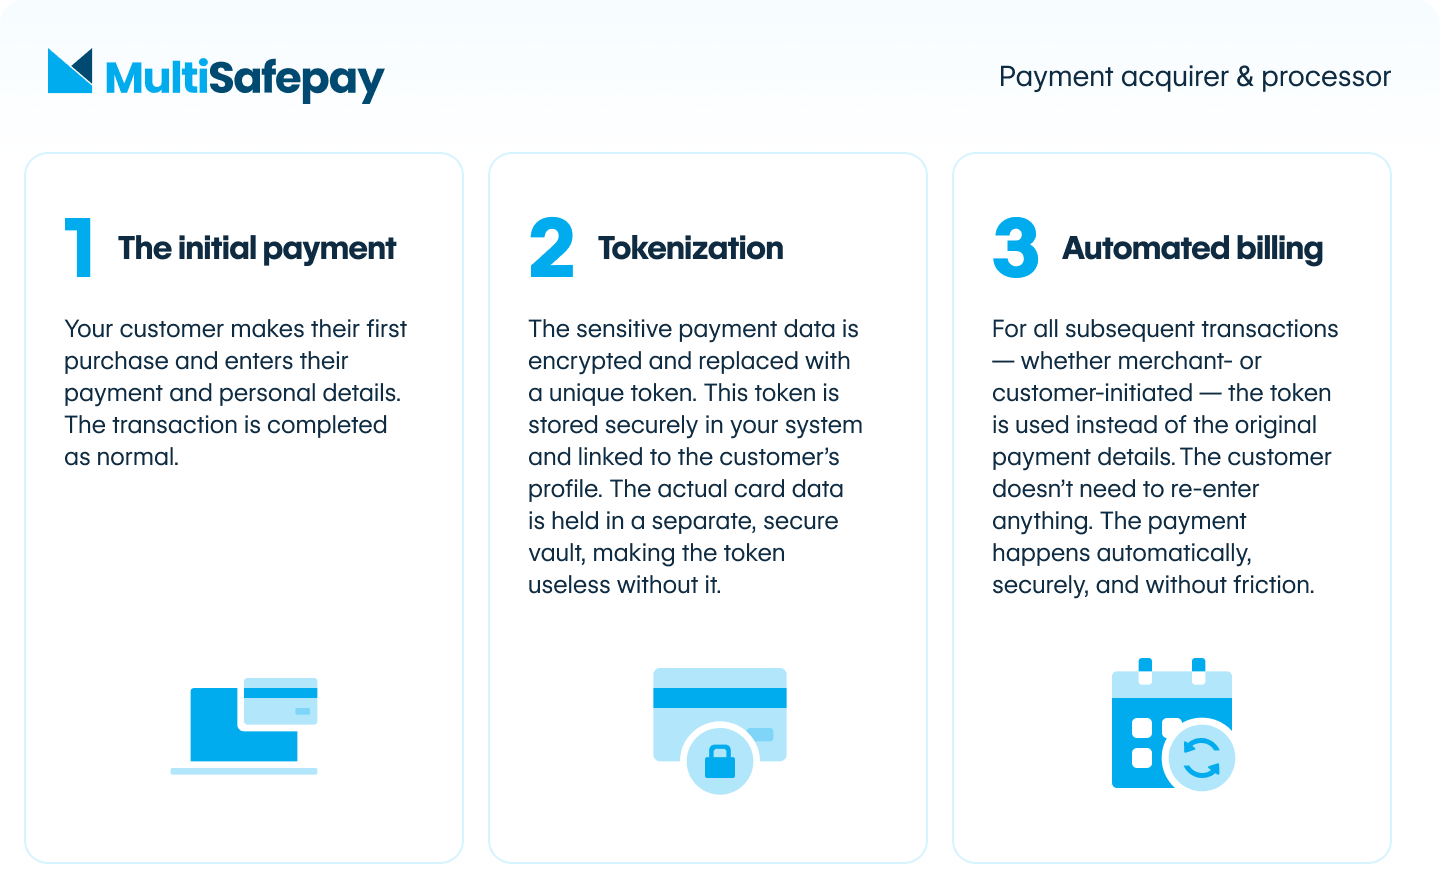
The technology that makes recurring payments possible is tokenization. Here's how it works in practice:
Step 1 — The initial payment. Your customer makes their first purchase and enters their payment and personal details. The transaction is completed as normal, with 3D Secure authentication required at this stage.
Step 2 — Tokenization. The sensitive payment data is encrypted and replaced with a unique token. This token is stored securely in your system and linked to the customer's profile. The actual card data is held in a separate, secure vault, making the token useless without it.
Step 3 — Automated billing. For all subsequent transactions — whether merchant- or customer-initiated — the token is used instead of the original payment details. The customer doesn't need to re-enter anything. The payment happens automatically, securely, and without friction.
The right payment strategies to keep recurring revenue flowing
Setting up the basic infrastructure is just the starting point. The merchants who get the most out of recurring payments are the ones who actively optimize how those payments are processed. Here are the key levers.
Tokenization and card-on-file
We've already covered how tokenization works, but it's worth emphasizing its strategic value. Storing payment details securely as a token doesn't just make repeat purchases easier. It also eliminates re-entry friction, reduces cart abandonment on follow-up orders, and enables one-click purchasing across your entire catalog. The longer a customer stays with you, the more valuable that stored token becomes.
Beyond PSP-managed vault tokenization, scheme tokenization solutions such as Visa Token Service (VTS) and Mastercard MDES offer an additional layer of security and interoperability, particularly relevant for recurring payment management. For a deeper look at how tokenization increases payment security and how your business can benefit, check our guide to tokenization.
SEPA Direct Debit
For European merchants, SEPA Direct Debit is one of the most cost-effective methods for collecting recurring payments. It's particularly well-suited for subscriptions and installment plans, where the merchant initiates the charge.
An essential note on SEPA Direct Debit: if you're processing recurring payments through direct debit, you must have a valid SEPA mandate in place. Without it, you don't have legal authorization to charge customers' accounts repeatedly. Even with a mandate, customers can reverse authorized charges within 8 weeks (56 days).
If direct debit is part of your recurring payment strategy, getting the mandate right is non-negotiable.
Once the mandate is in place, payments are processed automatically with low transaction fees and broad coverage across the eurozone.
Zero Authorization
Zero Authorization allows you to verify and register a customer's payment details without charging them immediately. This is particularly useful at the start of a free trial or when onboarding a new subscriber: you confirm the card is valid and tokenize it for future use, without triggering a payment that might create friction or doubt. When the billing period begins, the first charge goes through smoothly against already-verified details.
Smart routing
Not every payment method performs equally across issuers, geographies, and transaction types. Smart routing automatically directs each transaction through the path most likely to result in a successful authorization — taking into account issuer preferences, card type, and historical performance.
For recurring payments specifically, an acquirer and processor plays a particularly valuable role here. After the first 3DS-authenticated transaction, subsequent recurring charges don't require the customer to re-authenticate — the token handles everything. But that doesn't mean approval is guaranteed. MultiSafepay sits directly between you and the card schemes, running risk assessments in real time and routing each recurring charge through the optimal path.
For a closer look at how an acquirer and processor manages authentication and recovers declined transactions, this article covers it in detail.
Dunning and payment recovery
Not every charge succeeds on the first try. Failed payments are one of the most common causes of involuntary churn — and in many cases, they're recoverable.
Effective recurring payment management includes monitoring failed transactions, retrying charges at the right moment, and keeping stored payment details current as cards are reissued or renewed. The goal is to recover as much revenue as possible before a failed payment quietly becomes a cancellation.
If you'd like to learn more about recovery payment options, our team can help you identify the right recovery strategy for your business.
Commercial strategies to increase recurring payments
The payment infrastructure sets the foundation, but commercial strategy is what drives adoption. Here are the approaches that work best for merchants looking to grow their recurring revenue.
Discount annual subscriptions
Offering a discount for annual upfront payment is one of the simplest and most effective ways to increase recurring revenue. The customer saves money; you get a longer commitment and better cash flow. The right discount level depends on your margins and customer profile. The goal is to make the annual plan feel like an obvious choice without significantly eroding your revenue per customer. The reduction in churn alone often justifies the lower per-unit price.
Free trials
A free trial lowers the barrier to entry and gives customers a chance to experience your product before committing. Combined with Zero Authorization, you can capture payment details upfront, so the transition from trial to paid subscription happens automatically, without requiring the customer to take action. Keep the trial period long enough to demonstrate real value, but short enough to create a decision point.
Flexible billing
Rigid billing cycles are one of the reasons customers cancel. Offering flexibility — the ability to pause, skip, or adjust a subscription — reduces churn by removing the all-or-nothing dynamic. Customers who feel in control of their subscription are far less likely to cancel it entirely.
Bundling and upselling
Once a recurring relationship is established, it becomes significantly easier to grow the value of each customer. Bundles that combine complementary products at a slight discount, or tiered plans that offer more features at higher price points, give customers a reason to upgrade rather than leave. The key is timing: upsell offers land best when the customer has already experienced the core value of your product.
Why recurring payments are worth the investment
The case for recurring payments goes well beyond convenience. Done right, they change the economics of your business and the relationship you have with your customers. Here's where the impact shows up most:
- Predictable, compounding revenue. Recurring payments replace the uncertainty of one-off sales with a reliable baseline of income. That predictability makes it easier to plan inventory, manage cash flow, and invest in growth.
- Higher customer lifetime value. A customer who subscribes is worth more than one who buys once. Recurring relationships give you more touchpoints, more data, and more opportunities to deliver value — all of which increase the likelihood that the customer stays and spends more.
- Lower customer acquisition costs. Retaining an existing customer costs significantly less than acquiring a new one. A well-structured recurring payment model shifts the economics in your favor.
- Richer data and better decisions. Long-term customer relationships generate the kind of data that one-off transactions simply can't. Metrics like churn rate, engagement, and customer lifetime value become measurable and actionable.
- Reduced payment friction. Once enrolled, the checkout experience essentially disappears — nothing to fill in, nothing to approve, nothing to remember.
Recurring payments in practice: how Vitakruid does it
The best way to understand the impact of recurring payments is to see them working at scale.
Vitakruid, a Dutch supplement brand, built their subscription model in-house using MultiSafepay's API, with tokenization for iDEAL and credit card payments at its core. Their approach — which they call "herhaalgemak" (repeat-delivery convenience) — gives customers a 90-day supply on a rolling basis, with full flexibility to pause, adjust, or skip at any time.
Behind the scenes, tokenization handles the payment side automatically: the customer's first transaction creates a secure token, which is then used to process every subsequent delivery without storing sensitive card details or requiring manual intervention. Subscription orders flow through the same systems as regular orders, which means no separate processes and no additional operational overhead for the team.
The flexibility built into the model is what sets it apart. Customers can add or remove products, change quantities, bring deliveries forward, or postpone them. That level of control transforms a subscription from a commitment into a service — and, as Vitakruid's experience shows, it's what keeps customers from cancelling.
Start building your recurring payment model
Recurring payments aren't just a feature, they're a growth strategy. The right infrastructure, combined with the right commercial approach, can transform how your business generates revenue, retains customers, and plans for the future.
At MultiSafepay, we work with merchants at every stage of that journey — from setting up tokenization to optimizing approval rates and reducing churn through smart routing.
Ready to take your recurring payments to the next level?
Frequently Asked Questions
What are recurring payments?
Recurring payments are automatic charges made on a fixed or flexible schedule, based on upfront authorization from the customer. They cover subscriptions, installment plans, and any model where payment repeats without requiring action from either party each time.
What is the difference between merchant-initiated and customer-initiated recurring payments?
In a merchant-initiated transaction, the merchant triggers the charge automatically on a set schedule — as with a subscription. In a customer-initiated transaction, the customer decides when to buy, but stored payment details make the checkout instant. Both rely on tokenization to store and reuse payment data securely.
What is tokenization and why does it matter for recurring payments?
Tokenization replaces sensitive card data with a unique identifier — a token — that can be used for future transactions without exposing the original details. It's the technology that makes recurring payments both secure and frictionless: once a customer's details are tokenized, every subsequent charge happens automatically in the background.
Do I need a SEPA mandate for recurring payments?
If you're collecting recurring payments via SEPA Direct Debit, yes — a valid SEPA mandate is a legal requirement. Without it, you don't have authorization to charge customers repeatedly. Even with a mandate in place, customers can reverse authorized charges within 8 weeks (56 days). For card-based recurring payments, a mandate is not required, but the customer must give explicit consent at the time of the first transaction.
How can I reduce churn in my recurring payment model?
A combination of payment and commercial strategies helps. On the payment side: smart routing to maximize approval rates and Zero Authorization to validate cards before the billing cycle begins. On the commercial side: flexible billing that lets customers pause or adjust rather than cancel, and annual plans that lock in commitment upfront.